Category: Uncategorized

  • What You Paid, What You Owe & What Your Home Is Worth

    What You Paid, What You Owe & What Your Home Is Worth

    One of the conversations I find myself having with sellers is the difference between information that’s important to them and information that’s actually going to determine what a buyer is willing to pay for their house.

    Those aren’t always the same thing.

    I recently prepared a CMA for a seller, and when we talked afterward, three things kept coming up: her mortgage balance, an appraisal from a couple of years ago, and repairs and improvements she had previously made to the property.

    All three mattered.

    Just not necessarily in the way she initially thought.

    Your Mortgage Tells Me About Your Situation

    I absolutely want to know what you owe on your property.

    Your mortgage balance helps us estimate your equity and what your potential net might look like after the sale. It may even help you decide whether selling right now makes financial sense at all.

    Sometimes that number becomes a line in the sand.

    If the market supports a certain value, but you need substantially more than that in order for selling to make sense, then we may determine that now simply isn’t the right time to sell.

    But what you owe doesn’t determine what a buyer is willing to pay.

    A buyer isn’t looking at your mortgage balance and deciding how much you need to walk away with. They’re looking at your house and comparing it to the other options available to them in the market.

    An Old Appraisal Is Useful, But It Isn’t Today’s Market

    The second thing we discussed was a previous appraisal.

    If you have one, I absolutely want to see it. It gives me another piece of information about the property.

    But an appraisal is an opinion of value as of a particular point in time.

    Since then, other properties may have sold. New listings may have entered the market. Inventory may have changed. Buyer demand may be different. The condition of the property itself may have changed.

    So an appraisal from a couple of years ago can be useful information without necessarily telling us what buyers will pay today.

    The question isn’t only:

    What was the property worth then?

    We also have to ask:

    What does today’s market support?

    Past Repairs Don’t Always Equal Current Value

    The same principle applies to repairs and improvements.

    Maybe you renovated the property several years ago. You installed new flooring, painted, updated the kitchen or bathroom, or made other improvements.

    I want to know about those things too.

    But we also have to look at what condition those improvements are in today.

    If a property has been occupied for several years and experienced normal wear, tenant damage, deferred maintenance or other changes, we aren’t selling the house as it looked immediately after the renovation.

    We’re selling the house that’s standing in front of the buyer today.

    Some improvements absolutely can contribute to value. But money spent doesn’t automatically translate dollar for dollar into additional market value.

    Current condition still matters.

    Before We Get to the Bank’s Appraiser, We Have to Pass the Buyer’s Appraisal

    I don’t mean that the buyer is literally an appraiser.

    But before a lender ever orders an appraisal, somebody has to look at your property and decide that it’s worth making an offer on.

    Buyers are comparing.

    What else can I buy for this amount?

    What condition is it in?

    How does the layout compare?

    What features am I getting?

    What are the other houses in this price range offering me?

    In that sense, the buyer is making their own determination of value before we ever get to the formal appraisal.

    So What Does Determine the Price?

    This is where I bring the conversation back to today’s market.

    I’m looking at the solds because those transactions show us what the market has already proven.

    I’m paying close attention to the pendings because they give us insight into where buyers are making decisions right now.

    And I’m looking at the active listings because those properties are your competition.

    Then we compare the property itself: condition, layout, square footage, bedrooms, bathrooms, improvements, days on market and the seller’s timeline.

    That’s where our pricing conversation starts.

    Your mortgage matters because it helps me understand your financial position.

    Your previous appraisal matters because it gives us additional information.

    Your improvements matter because they help tell the story of the property.

    But none of those gets to dictate what somebody has to pay you today.

    Your history with the property helps me understand your situation. Today’s market helps me understand your price.

    Watch the Full Conversation

    I broke this seller conversation down further in the latest episode of Road to 50 Listings.

    If you’re considering selling and want to have a conversation about what the current market may support for your property, you can also schedule a Listing Strategy Call with me.
  • A Day in the Life: What Leverage Looks Like in Real Estate

    A Day in the Life: What Leverage Looks Like in Real Estate

    What Leverage Actually Looks Like in Real Estate

    The word leverage gets thrown around a lot in real estate.

    Usually, when we hear it, we think about hiring assistants, building teams, creating systems, or finding ways to get more done without doing everything ourselves.

    But sometimes leverage is much simpler than that.

    Sometimes it looks like somebody answering the phone and saying, “I got it.”

    Recently, one of our Realtors at Williams-Claytor Realty was out of the office while working through a client transaction. A foundation specialist needed to meet at the property, and the appointment still needed to happen.

    Instead of the file sitting still until the agent was available again, she reached out for help.

    I stepped in.

    I met the foundation specialist at the property, walked through what needed to be addressed, and helped make sure the information could get back to the Realtor and her client.

    Nothing particularly glamorous happened.

    But the file kept moving.

    And I think that’s a good example of what leverage actually looks like in real estate.

    Your Business Can’t Stop Every Time You’re Unavailable

    Real estate is a relationship business, and I believe strongly in taking ownership of the people and transactions you’re responsible for.

    But taking ownership doesn’t mean you have to physically perform every task yourself.

    There are going to be times when you’re at another appointment, working with another client, out of town, with your family, or simply unable to be in two places at once.

    The question becomes:

    What happens to your business when you’re not available?

    If every decision, appointment, vendor interaction and problem has to wait for you personally, eventually you become the bottleneck.

    That’s difficult to scale, but more importantly, it can affect the client’s experience.

    Leverage Doesn’t Mean Doing Less

    I think this is where leverage can sometimes be misunderstood.

    Leverage isn’t about avoiding responsibility.

    It’s about building relationships and resources around yourself so you can fulfill that responsibility better.

    For a Realtor, that could mean having relationships with inspectors, contractors, lenders, title companies and other professionals you trust.

    It could mean having another agent who can open a door when you’re unavailable.

    And in our case, it can mean having additional resources within the brokerage that agents can lean on when something needs to get done.

    The agent still owns the client relationship.

    The agent still owns the responsibility.

    But everything doesn’t have to depend on that one person physically being there.

    The Environment Around an Agent Matters

    This experience also reminded me why I’ve become increasingly interested in the environment we create around Realtors.

    We spend a lot of time talking about leads, scripts, commissions and production.

    Those things matter.

    But so does having an environment where you can ask a question, shadow someone who’s done it before, call someone when you need help, or simply say, “I can’t be there. Can somebody cover this for me?”

    That support becomes even more important as your business grows.

    Because eventually, growth forces you to recognize something:

    You can’t be everywhere.

    The goal isn’t to become less involved.

    The goal is to build enough trust, relationships and infrastructure around your business that your clients continue to receive a high level of service even when you’re not the person standing in the room.

    A Day in the Life

    This particular foundation inspection was only one part of my day.

    That’s one of the things I enjoy about documenting more of the behind-the-scenes side of what I do.

    My days in real estate can move between working with buyers and sellers, supporting our Realtors, dealing with contractors and properties, handling inspections, solving problems, and working on the business itself.

    Sometimes the best lessons don’t come from sitting in front of a camera teaching.

    They come from simply showing the work.

    This was one of those days.

    A Realtor was out of the office.

    Her client still needed something handled.

    She leaned on the people around her.

    And the file kept moving.

    That’s leverage.

    Want to see what the day actually looked like?

    Watch the full behind-the-scenes video below and come spend part of the day with me.

  • Why This Rental Sold for Full Asking Price

    Why This Rental Sold for Full Asking Price

    When people hear that a rental property sold for full asking price, the first assumption is usually that it was because of great marketing.

    Marketing certainly plays an important role, but in this case, I believe the biggest reason the property sold so successfully started years before it ever hit the market.

    If you rather watch than read, Watch Episode 2 of Road to 50 Listings.

    One of my recent listings was a rental property that sold for $135,000 at full asking price. While I was proud of how we marketed the property, what gave buyers confidence was everything the owner had done leading up to the sale.

    The property had been professionally managed, the financial records were organized, and the tenant had a consistent payment history. Buyers were not left guessing because the information they needed was readily available. That level of preparation reduced uncertainty and made the property much more attractive.

    Another factor was the seller’s position. Because the property generated reliable income and the owner had built equity over time, there was no pressure to accept the first offer that came along. Strong cash flow often gives sellers more flexibility during negotiations.

    One lesson this transaction reinforced for me is that successful real estate sales rarely begin on listing day. They begin with years of good decisions that make a property easier to own, easier to evaluate, and ultimately easier to sell.

    That is one of the reasons I started documenting my Road to 50 Listings journey. Every transaction teaches me something, and my hope is that by sharing these experiences, homeowners, landlords, and real estate investors can gain practical insights that help them make better decisions.

    Want to see how this transaction unfolded from start to finish? Watch Episode 2 of Road to 50 Listings on YouTube, where I walk through the listing, explain why I believe this property earned full asking price, and share the lessons I took away from the experience.

    If you’d like to follow the rest of the journey, be sure to check back for future articles as I document each listing, the lessons I learn, and the strategies I’m using to reach 50 listings.

  • 9 Questions Realtors Should Ask to Spot Tire Kickers

    9 Questions Realtors Should Ask to Spot Tire Kickers

    If you’re a Realtor or seller, you’ve dealt with them.

    Buyers who sound ready… but never actually move forward.

    They’ll say things like:

    • “I’m a cash buyer”

    • “We’re just waiting on the right opportunity”

    • “We’re serious, just taking our time”

    And then weeks go by… no offer, no movement, just time wasted.

    The truth is – most of this can be avoided upfront.

    Why This Matters

    Every showing, every call, every walkthrough costs you time.

    If you’re not filtering properly, you end up:

    • Dragging listings longer than necessary

    • Losing momentum with serious buyers

    • Frustrating sellers (or yourself as the investor)

    The goal isn’t to push people away – it’s to identify who’s actually ready to move.

    The Solution: Ask Better Questions Early

    In this video, I break down 9 key questions you should be asking every buyer before you invest real time into them.

    These questions will help you:

    • Quickly identify real buyers vs. browsers

    • Understand their financial position

    • Set expectations early

    • Protect your time and your deals

    Watch the Full Breakdown 👇🏾

  • Understanding Real Estate Partnerships: Equity vs. Debt

    Understanding Real Estate Partnerships: Equity vs. Debt

    In the dynamic world of real estate development, partnerships play a pivotal role in shaping the success and trajectory of projects. Understanding the nuances between equity and debt partners is crucial for investors and developers seeking the most suitable collaboration to propel their ventures. In this blog post, we will unravel the key disparities between equity and debt partnerships, shedding light on their unique characteristics and implications for real estate projects.

    Equity Partnerships:

    1. Ownership Stake:

    Equity partners inject capital into a real estate venture, securing an ownership stake in the property. This ownership provides them with a vested interest in the project’s success.

    2. Profit Sharing:

    Unlike debt partners, equity partners actively share both the profits and losses of the project. Their returns are intricately tied to the performance of the property, fostering a collaborative approach to success.

    3. Active Involvement:

    Equity partners often assume an active role in decision-making and property management. This engagement allows them to contribute to the project’s strategy and navigate potential challenges collaboratively.

    4. Long-Term Commitment:

    Equity partnerships are typically characterized by long-term commitments, with the partner’s investment at risk throughout the project’s duration. This prolonged engagement fosters a sense of shared responsibility and commitment to the project’s success.

    Debt Partnerships:

    1. Lender Role:

    A debt partner, commonly referred to as a lender, acts as a financial supporter by providing a loan for the real estate project. However, unlike equity partners, they do not acquire ownership in the property.

    2. Fixed Returns:

    Debt partners receive fixed interest payments on the loan amount, irrespective of the property’s performance. This predictable return structure offers stability but lacks the potential for additional profits associated with equity partnerships.

    3. Limited Involvement:

    Debt partners typically assume a passive role in the project, refraining from active participation in decision-making or property management. Their focus is primarily on the financial aspect of the partnership.

    4. Short-Term Commitment:

    Debt partnerships are characterized by shorter commitments, usually aligning with a predetermined loan term. Once the loan is repaid, the partnership concludes, providing a defined timeline for involvement.

    Conclusion:

    In the intricate landscape of real estate partnerships, the choice between equity and debt partnerships hinges on the specific needs and goals of investors and developers. Equity partnerships offer the potential for higher returns but involve shared ownership and risks, demanding a long-term commitment. On the other hand, debt partnerships provide financing with a predictable cost, devoid of ownership but offering a structured, short-term commitment. Ultimately, understanding these distinctions empowers real estate stakeholders to strategically leverage partnerships, aligning them with their unique project aspirations and risk tolerance.

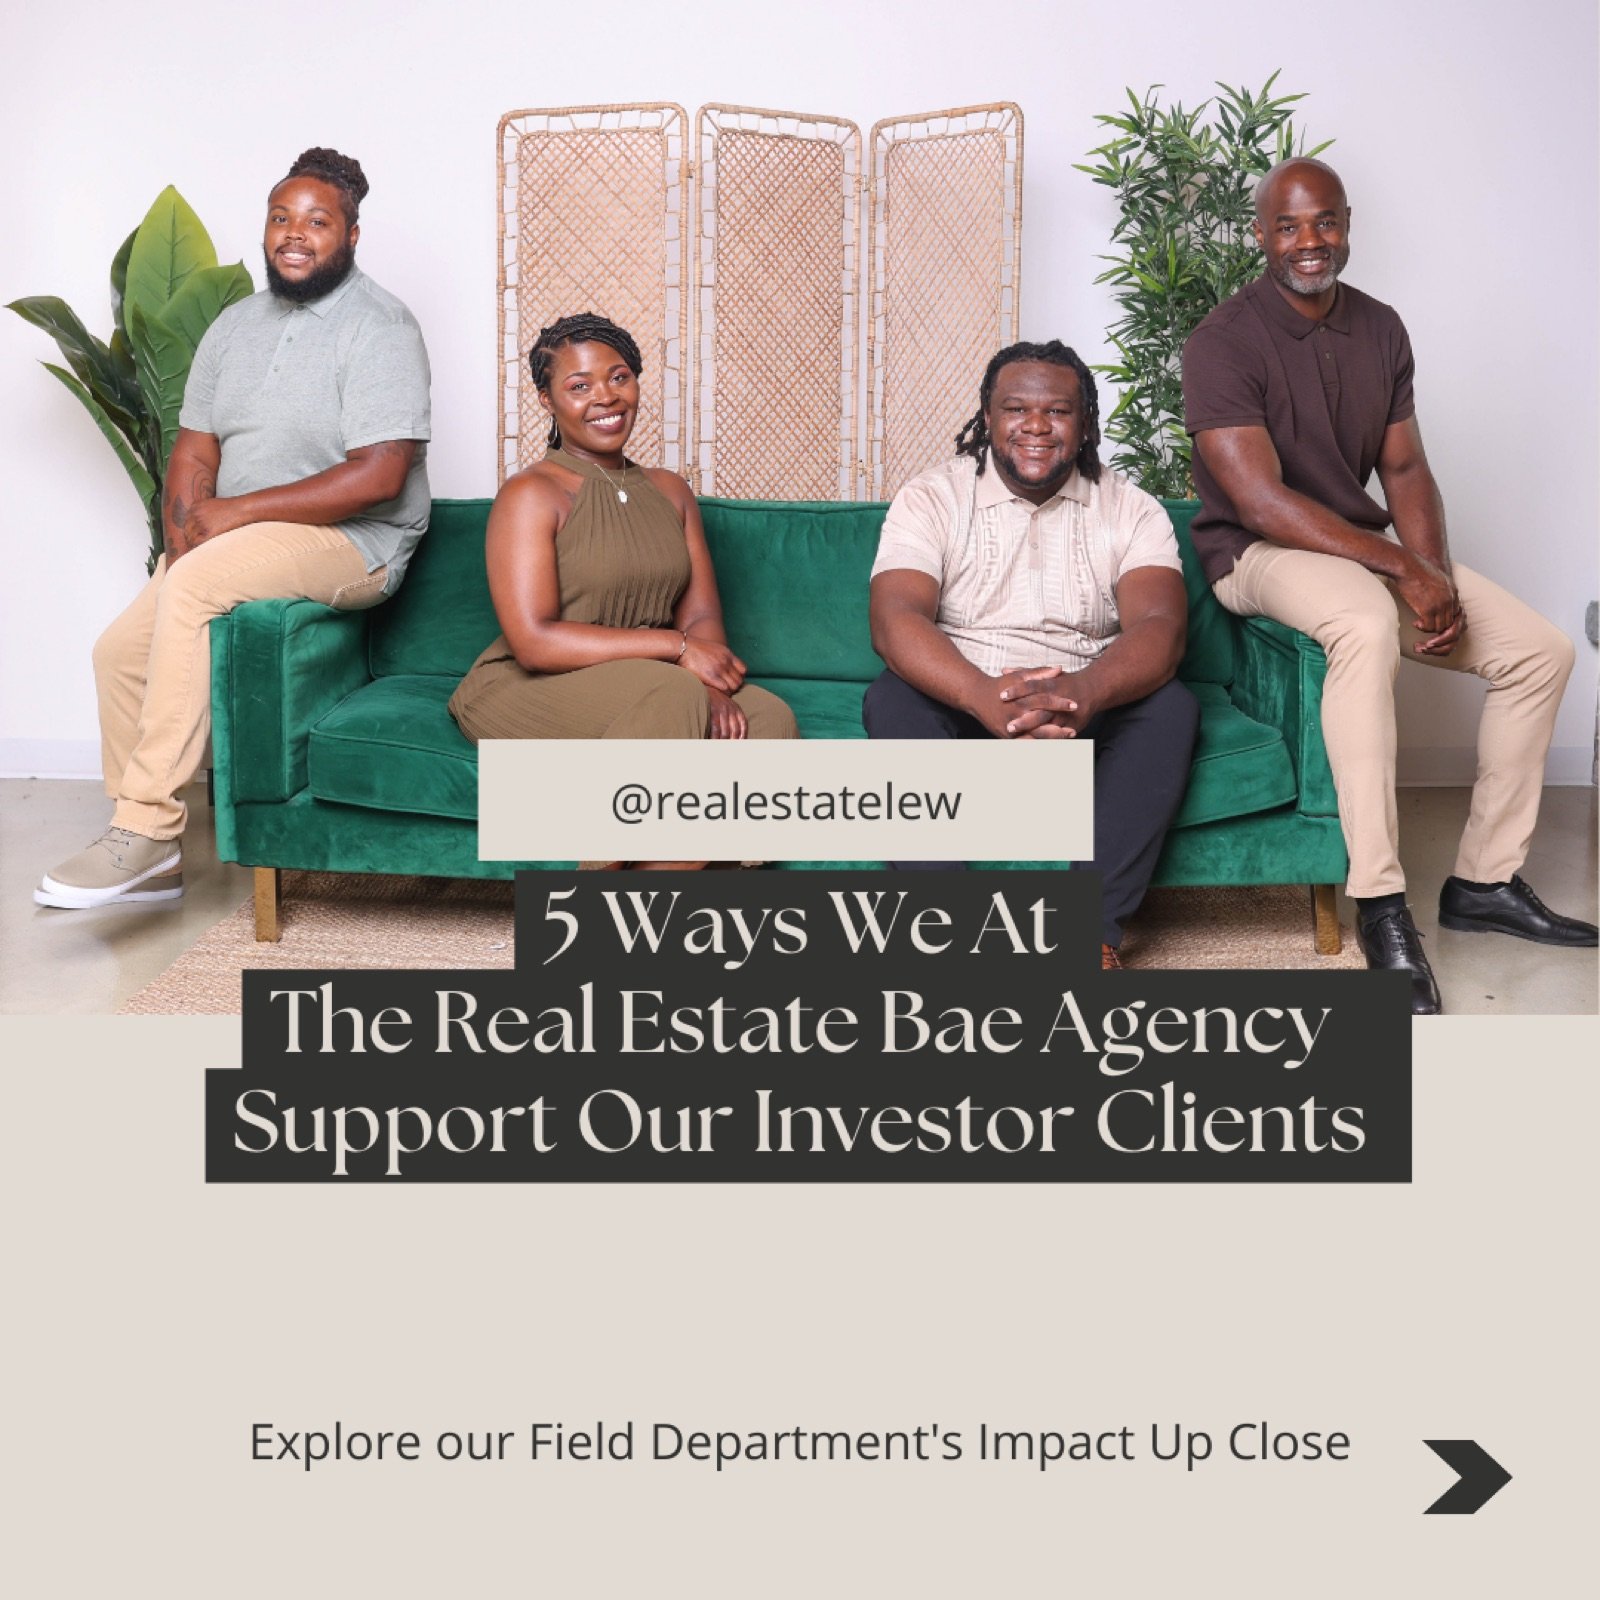
  • 5 Ways That We Support Our Clients At Our Turnkey Real Estate Agency

    5 Ways That We Support Our Clients At Our Turnkey Real Estate Agency

    At the heart of our Field Department with our turnkey real estate agency is an unwavering commitment to client success. We serve as dedicated partners, guiding clients through every step of their property journey. From drafting up thorough scopes of work 📋to overseeing seamless renovations🛠️, we’re by their side.

    Our expert team orchestrated the entire process, coordinating contractors, ensuring quality work, and maintaining clear communication. With us, clients can confidently entrust their real estate ventures, knowing that we’re here to provide personalized support, valuable insights, and a tailored experience that maximizes their returns while minimizing their stress.